The Bond Market is the House
By Ben Lord - 14 September 2026
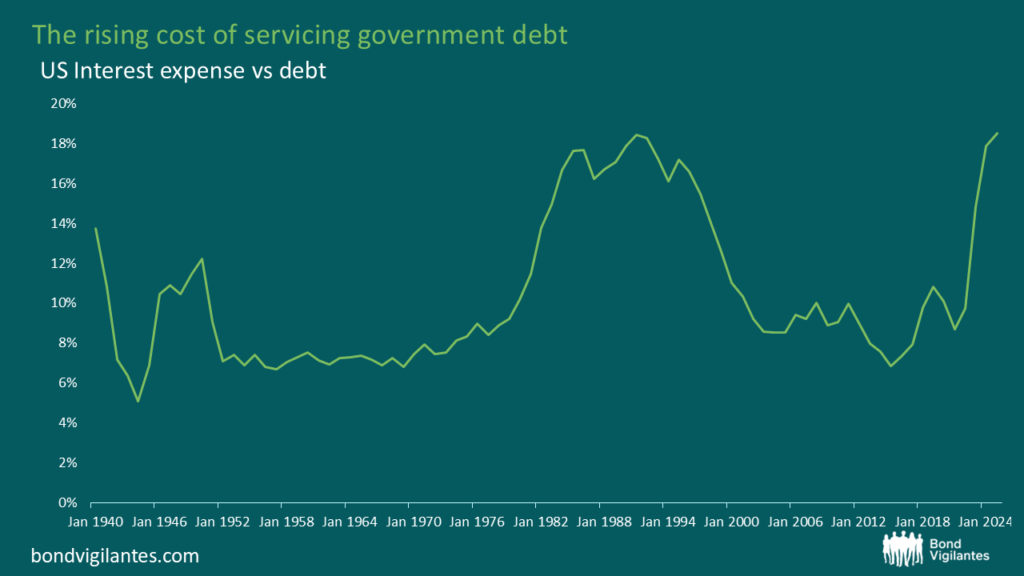
The bond market has taken control from Warsh and Bessent, and in some ways is now testing or even tormenting them.
Discover historical blogs from our extensive archive with our Blast from the past feature. View the most popular blogs posted this month - 5, 10 or 15 years ago!
The bond market has taken control from Warsh and Bessent, and in some ways is now testing or even tormenting them.
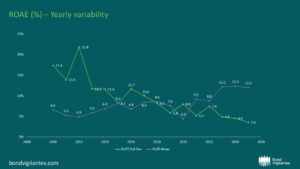
For those who follow bank returns for a living, Japan’s push toward low-to-mid-teen RoE/RoTE (return on equity/return on tangible equity) over the medium term is one of the most striking re-ratings in the sector – a genuine regime change against the mid-to-high single digits of the past few decades.
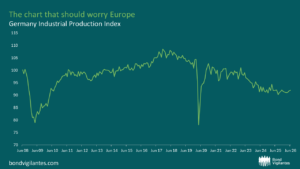
For most of the euro’s existence, investors have operated under an implicit assumption: Germany would always be there.
What can the UK government learn from British Airways’ handling of the Avios programme? Quite a lot, as it turns out.
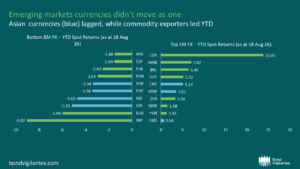
At the start of the Year of the Fire Horse, we argued that Asian currencies were approaching a potentially important turning point. Stronger trade balances and evolving capital-allocation patterns had the potential to challenge several years of US dollar dominance.
It is 20 years ago this month that I sat in a pitch and listened to an investment bank describe their latest stroke of genius. In 2006, the Constant Proportion Debt Obligation (CPDO) was hailed as a financial innovation that appeared to offer something for nothing: a AAA-rated security paying a meaningful premium over cash.
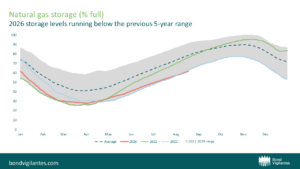
European natural gas prices are rising again, storage levels are lower than expected, and memories of the 2022 energy crisis remain fresh. But does this really constitute a new energy crisis for Europe, and more importantly for bond investors, does it change the ECB’s policy outlook?
Why aren’t we talking more about El Niño?
In a world of tight credit spreads, one rating bucket flashes value. The European CCC index offers 1,306 bps over government bonds, suggesting generous compensation for taking credit risk.
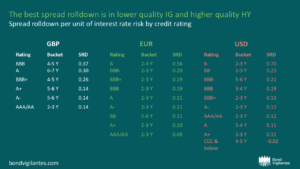
We previously blogged on which area of government bond curves investors should have exposure to if they want to receive the greatest benefit from the passage of time. In a normal/upwardly sloping yield curve environment, the yield of a bond will fall (and its price will rise) the closer it gets to maturity. Or, as it rolls down the curve.
We are very sorry to share the news that Jim Leaviss passed away on 23 July 2026, aged 55.
For years, Australian residential property has been viewed as a one-way bet. Mention the possibility of falling house prices and you’re often met with disbelief. Population growth, constrained housing supply and a deeply ingrained belief that property always goes up have combined to create one of the most expensive housing markets in the developed world.
And so, the semi-finals have concluded and we have our finalists. Spain and Argentina will face each other in the World Cup Final on Sunday.
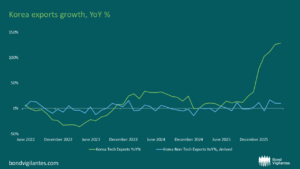
Korea is one of the clearer beneficiaries of the global AI investment cycle. Its equity market has reflected that. Its currency and government bond markets have not.
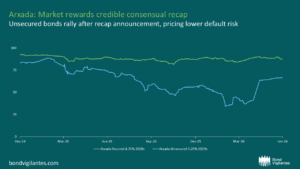
The market increasingly treats LME risk as synonymous with coercion and value transfer. Sponsors have a range of technologies: dropdowns, up-tierings, double dips as well as other non-pro-rata outcomes. In structures with weak protections that instinct is understandable, but increasingly incomplete. Some credits with high LME optionality are delivering negotiated, consensual outcomes that preserve value, and in some cases, unlock upside.
Sign up to the Bond Vigilantes mailing list to ensure you never miss a great article from our expert Bloggers. We will email all new articles to your inbox, meaning you can stay on top of the world of Bonds.
I confirm that I would like to receive information about Bond Vigilantes and products and services from M&G Securities Limited.
We will use the email address and personal data you have shared with us to send you this information. For existing customers, submitting your contact details and requesting to receive this information from us, will replace any earlier choices you have made in respect of marketing information.
You can unsubscribe from marketing at any time, at which point we will not send any further marketing information to you, by selecting the unsubscribe link in all communications.