

What the Past Gets Wrong About the Future
Paramount Skydance’s (PSKY) recent $110 billion acquisition of Warner Bros. Discovery (WBD) was one of the largest corporate takeovers in history. Despite the deep equity pockets acquiring parties, it required a massive $52 billion in new debt financing across investment-grade bonds, high-yield bonds and leveraged loans, making it one of the largest debt financings in history. For high-yield investors, we estimate that the $12.4 billion of new bonds, combined with the existing bonds, will represent somewhere between 1.3% and 2.0%+ of the ICE BofA High Yield Global and US Indices respectively, making it difficult for index-aware managers to ignore, regardless of their reservations or enthusiasm for the combination.
This got us thinking about not only the scale of the transaction, but about a blog Luke published nearly a decade ago and how dramatically US TMT has evolved since then. In 2017 when the blog was published, the US TMT sector was rife with merger and consolidation speculation as companies navigated a rapidly changing competitive environment and shifting consumer behaviour. US spreads had largely recovered from the Energy downturn and base rates remained low, encouraging acquisitions that were hopefully accretive and, no doubt, beneficial to management teams’ incentive plans as well. Our analysts put together the chart below summarising many of the mergers, acquisitions and industry combinations being discussed across the sector. https://bondvigilantes.com/blog/2017/04/telecom-acquisition-spree-set-kick-off-u-s/
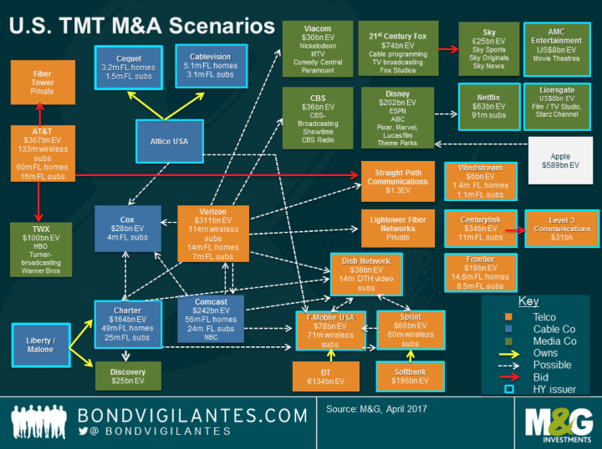
It wasn’t intended as a forecast, simply a snapshot of what investors, analysts and management teams were opining on, and of the animal spirits running through an industry where seemingly every scenario was being bandied about.
A number of the arrows came to fruition. AT&T acquired Time Warner. Disney bought most of Fox’s entertainment assets. CenturyLink acquired Level 3 and T-Mobile eventually merged with Sprint. What stands out today, though, is not the transactions themselves, but how the sector evolved in ways few could have fully foreseen.There’s probably an Oracle pun in there somewhere, but let’s carry on.
Netflix, Apple and Amazon are the most interesting. Netflix, which had what now seems like a quaint $63 billion enterprise value (EV), proved its doubters wrong by becoming the dominant global streamer and media company ahead of traditional rival media companies like Disney. Apple was viewed as a potential consolidator with the financial firepower to move on any media company but held back and pursued an organic path to build its content. And Amazon the once ‘humble’ online bookseller clearly had greater ambitions. All three have since spent billions on original content, even winning Oscars and Emmys along the way (not that anyone cares anymore). They have also acquired rights to established fan franchises and are increasingly competing for sports broadcast/streaming rights across the globe. And let’s not forget Amazon’s cloud computing and AI ambitions, but that’s another blog.
John Malone’s Liberty Media 2017 purchase of Formula One, of all things, may have been a precursor of other unanticipated twists the sector would encounter. From Larry Elison’s Oracle effectively backstopping PSKY’s takeover of WBD to SoftBank shifting from selling Sprint to making enormous bets on AI, and even Elon Musk entering the fray with Starlink acquiring spectrum from satellite TV provider DISH.
Then there were the incumbent TMT players. Technology changed consumer behaviour in ways that were perhaps not fully appreciated at the time, leaving some previously dependable businesses looking like the proverbial, if slightly overused phrase, “melting ice cubes”. Add some aggressive behaviour towards bondholders from a handful of billionaire owners, and the story became even more interesting.
Time Warner, after a myriad of twists and turns, eventually became Warner Bros. Discovery and eventually descended into high yield due to elevated leverage, with continued declines in linear-TV that streaming/studio growth failed to offset. As noted WBD was purchased by PSKY, however, few would have anticipated that Paramount would have to outbid former DVD home delivery antagonist Netflix for the business.
Altice USA was once viewed as an active consolidator, combining Cablevision and Suddenlink to capture synergies and market share. Ultimately, however, competition, subscriber losses and mounting leverage made things more challenging. The relationship with creditors descended into litigation over liability management and alleged asset transfers, claims the company disputes. Even the Altice USA name has gone, replaced by Optimum, continuing the time-honoured corporate tradition of changing names in difficult times.
Charter evolved from a dependable steady growth story, to a mini boom during COVID, and now on to a more testing future as it faces the cable sectors secular challenges from rising broadband competition. With a leveraged balance sheet relative to its telco peers and Comcast, Charter has reacted by progressively tightening its credit metrics targets from 4.0-4.5x to now looking to be 3.5x within 3 years, aided by the recent Cox merger and its associated US$1bn synergies and still meaningful FCF. A subsequent merger with Comcast further down the line would further offer the same benefits, so one to watch and with Charter being is a significant index constituent, it also means market participants need to pay close attention too.
Satellite TV player DISH spent billions accumulating spectrum to reinvent itself as a wireless competitor while its core satellite TV business declined and debt piled up. Some suspected that DISH’s colourful poke playing owner Charlie Ergen was accumulating valuable spectrum less to build a viable wireless competitor than to monetise those assets later at a premium. Perhaps they were right, as DISH has since sold billions of spectrum to AT&T and SpaceX. In the interim, however, bondholders endured asset-transfer disputes, distressed exchanges, prepackaged bankruptcies and plenty of litigation and lawyers’ fees. Again, probably a blog on its own.
Just over a decade ago, US Energy was high yield’s problem child, littered with restructurings and bankruptcies, while TMT was seen as safe and dependable, supported by recurring revenues and predictable consumer behaviour. Meanwhile, technological advances lowered production costs and years of balance-sheet discipline, arguably imposed by a market that refused to fund leveraged growth, left most energy companies with stronger balance sheets and less sensitivity to commodity prices. Today, however, TMT investors face many of the challenges once reserved for energy. Quite a reversal of fortunes.
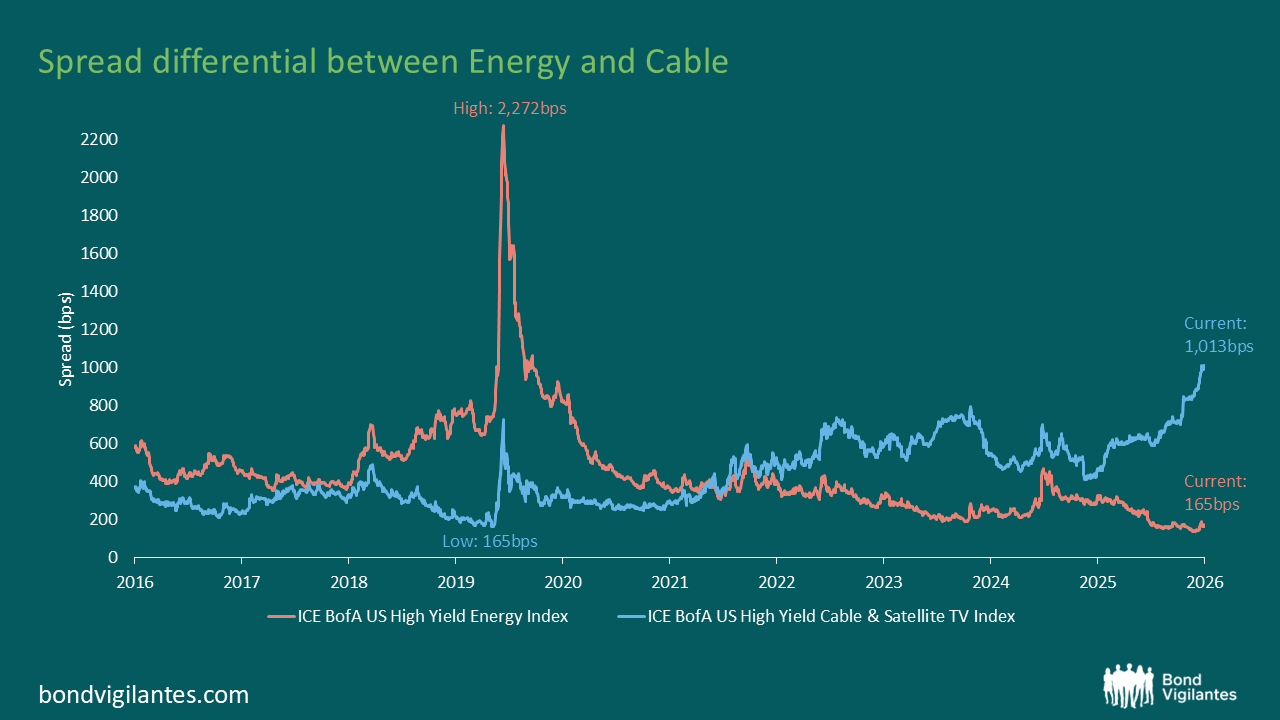
Source: Bloomberg H0EN, H0CV, data as at 12 October 2026. Spread = Gov OAS.
When it comes to the fates of TMT and Energy, I think it’s fair to question if hubris and/or complacency set-in among management teams and investors writ-large . Leaving aside individual company circumstances, the progression of the two sectors provides valuable lessons when it comes to broader market evolutions and how to avoid or exploit such changing tides. It reminds me of the last line in F. Scott Fitzgerald’s The Great Gatsby: “So we beat on, boats against the current, borne back ceaselessly into the past….”
The value of investments will fluctuate, which will cause prices to fall as well as rise and you may not get back the original amount you invested. Past performance is not a guide to future performance.